The deals desk is busy again, but the logic has changed. The acquisitions and deal chatter logged this week share one thread: buyers are no longer paying for growth stories or brand momentum, they are paying for specific capabilities they cannot easily build themselves, and they are willing to wait years for the payoff. The CrowdStrike-Zscaler talks, Intel's Classiq acquisition and even Sony's oddly priced Walkman pre-orders all reflect a market in which strategic fit, not cheap capital, is doing the work.
Consolidation Comes Back to Security
The most consequential item on the beat is the reported approach by CrowdStrike Holdings Inc. toward Zscaler Inc. According to Bloomberg, sources say the two are in talks and that a deal could "come together soon," though those same sources caution it may still fall through. That caveat matters: reports of talks are not deals, and this column treats them as such. What is notable is the market reaction. Zscaler's share price jumped on the report, which tells you investors read a combination of two large, publicly traded security vendors as credible rather than fantastical.
The reason is not hard to find in the material. Both companies sell cybersecurity software to enterprises, and a tie-up would concentrate two distinct franchises under one roof. For US technology companies, the signal is that scale in security is being pursued through acquisition again, not merely through internal product expansion. For US enterprise customers, the practical question is whether consolidation narrows the vendor field they negotiate with. Neither of those questions is answered by a report of talks, but both are now live.
Intel Buys a Business Model, Not Just Code
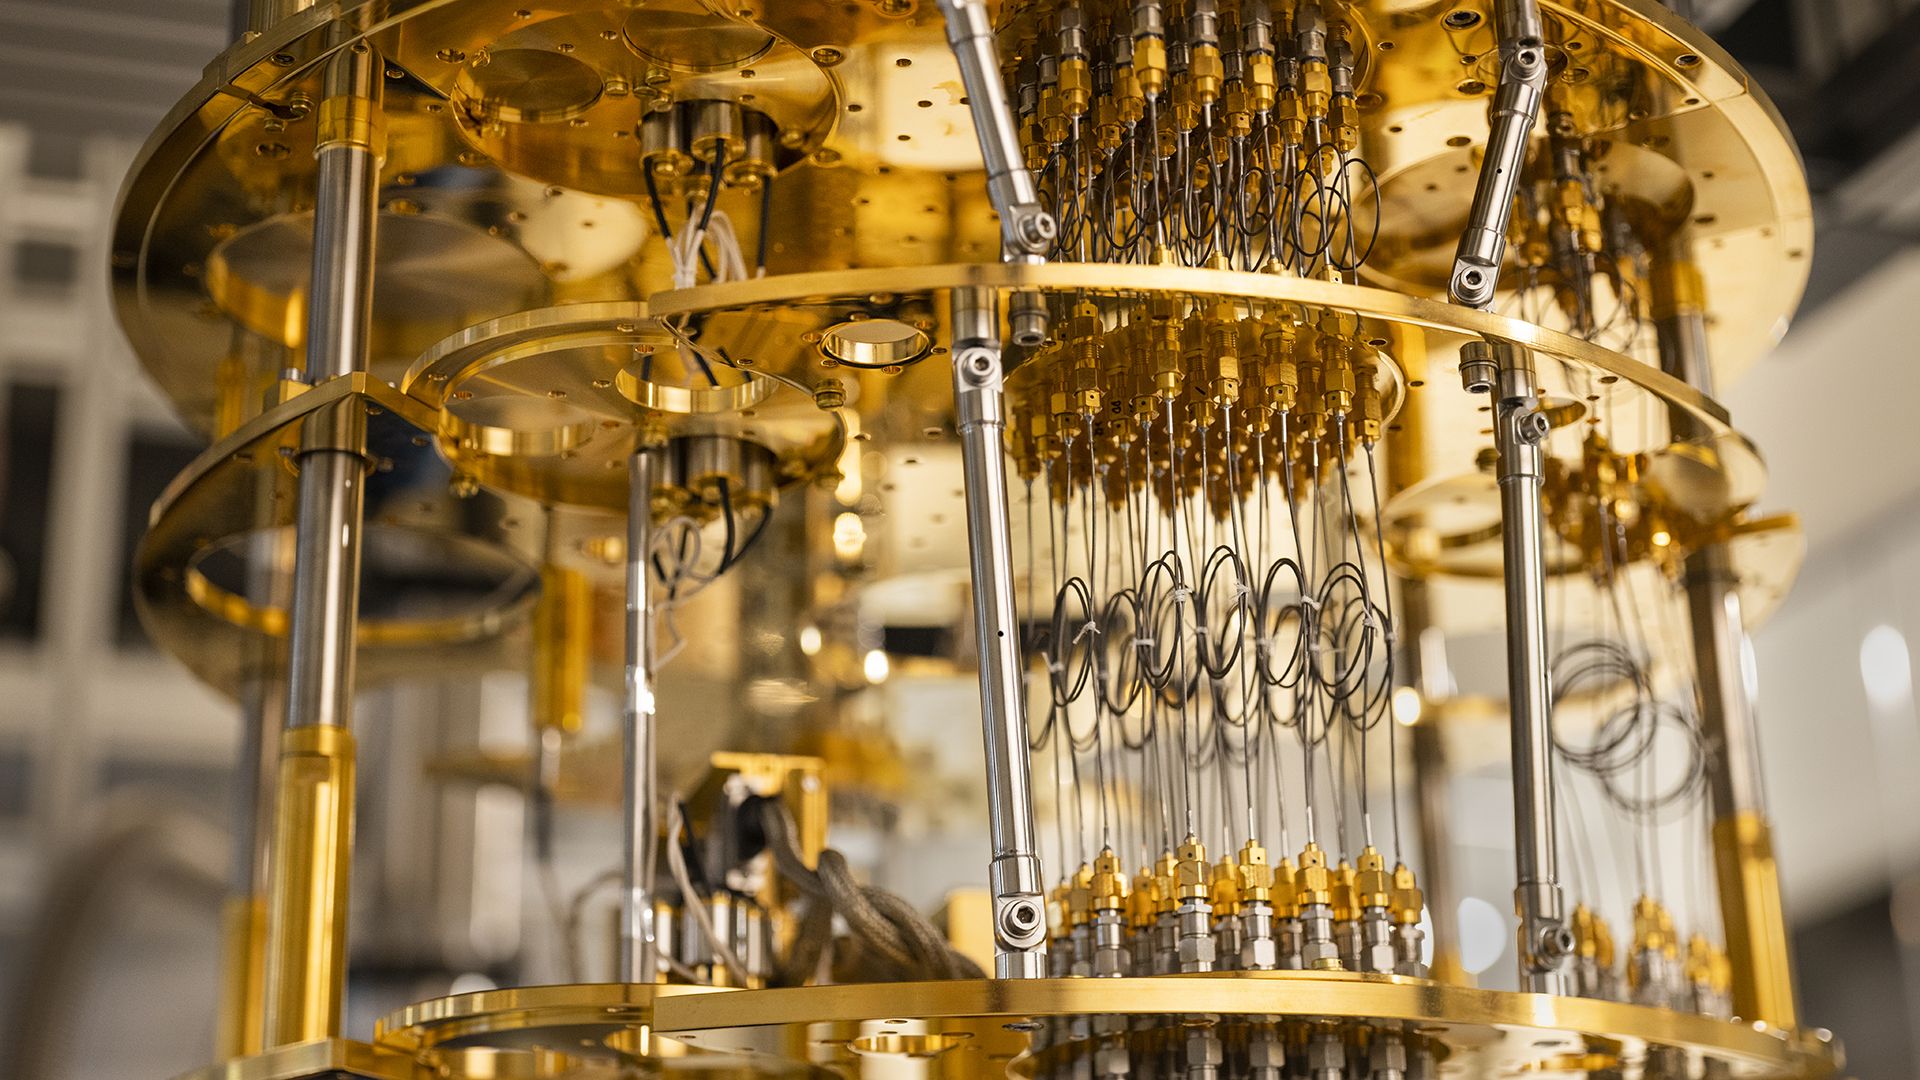
The Intel story is the cleanest illustration of the pattern. As Tom's Hardware reported, Intel aims to turn its quantum computing research effort into a commercial business by combining its silicon spin-qubit technology and manufacturing capabilities with Classiq's established software platform and customer base. The deal, per that report, positions Intel as a leading vendor of qubit chips and is expected to close by the first half of 2027.
Read that closely. Intel is not buying a lab curiosity. It is buying the software layer and the customers that convert a research program into revenue. The long closing window, stretching into 2027, is itself a fact worth noting: this is a patient deal, structured around a multiyear commercial transition rather than an immediate earnings bump. Quantum computing remains a research-stage market, and Intel's bet is that the company that owns both the qubits and the software platform sits closest to commercial viability. For the US market, that is a bet on domestic semiconductor and software leadership in a field where the commercial timeline is still uncertain.
The Walkman as a Pricing Test
Sony's new digital Walkmans look like an outlier on a deals beat, and in one sense they are: this is a product launch, not a transaction. But the story belongs here because it is a pricing decision, and pricing decisions are the smallest unit of deal logic. As Engadget reported, Sony opened pre-orders for three new Walkmans with jaw-dropping price tags, and the outlet's own framing asks what the money buys and why the numbers may not add up.